|
Royal Swedish Academy Awards 2026 Economics Prize
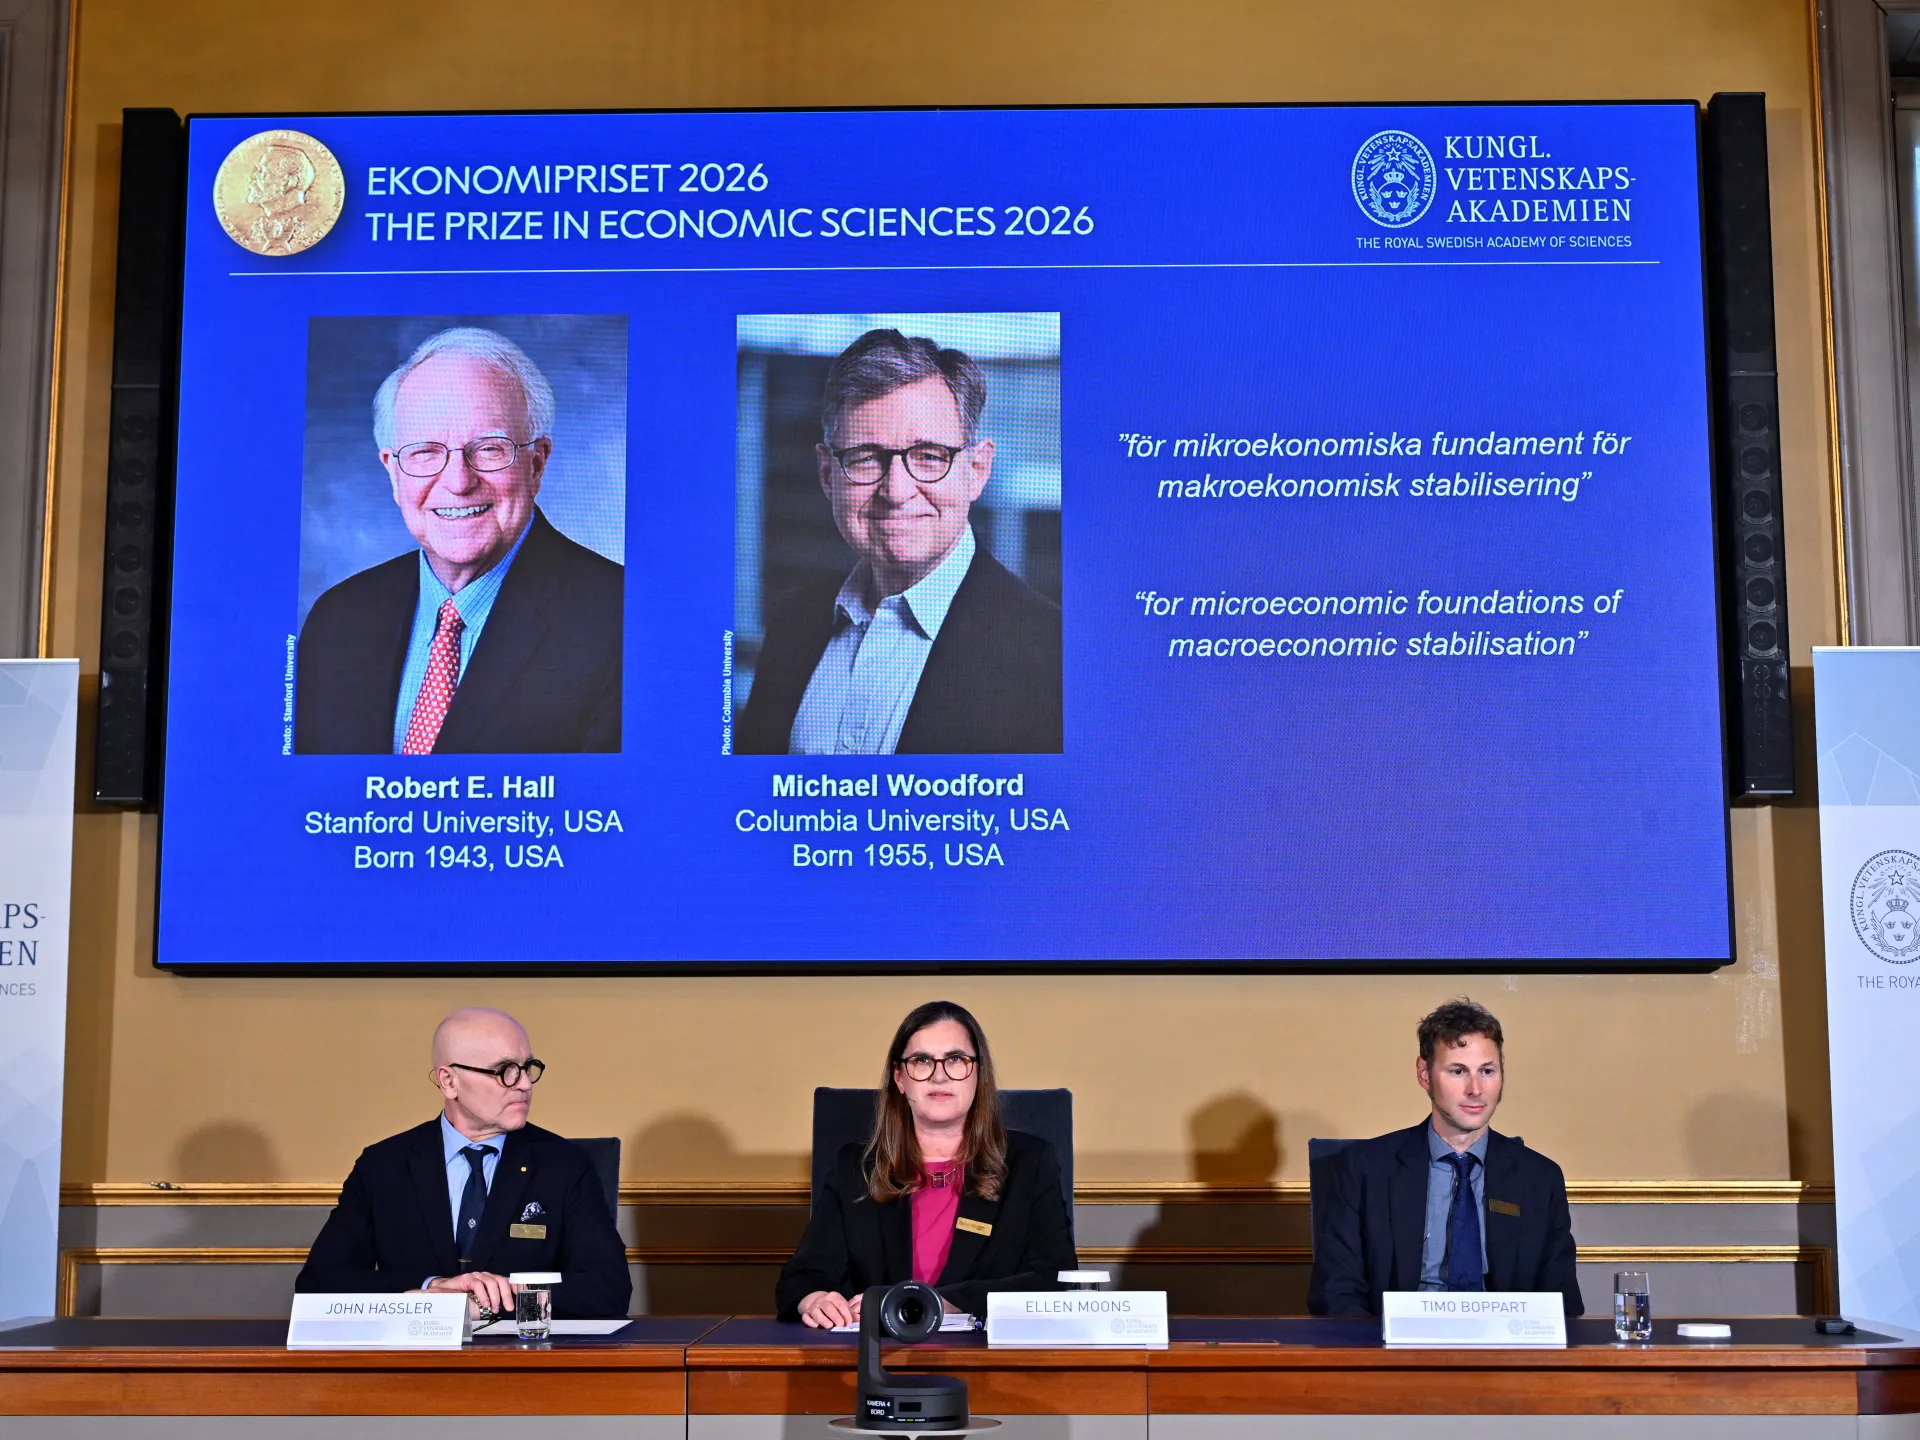
The Royal Swedish Academy of Sciences awards the Sveriges Riksbank Prize in Economic Sciences jointly to Robert E. Hall (Stanford University) and Michael Woodford (Columbia University). The 2026 award recognises their work on “microeconomic foundations of macroeconomic stabilisation.”
2026 Sveriges Riksbank Prize in Economic Sciences:
| Dimension | Key Details |
|---|---|
| Awarding body | The prize is awarded by the Royal Swedish Academy of Sciences. |
| Official name | The official name is “The Sveriges Riksbank Prize in Economic Sciences in Memory of Alfred Nobel.” |
| Common name | The prize is commonly called the Nobel Prize in Economics. |
| Recognised contribution | The research provides for the development of New Keynesian models used by central banks and governments to manage economic fluctuations. |
| Robert E. Hall: Consumption theory | Hall’s Random Walk Hypothesis of Consumption (1978) provides for the statement that, under life-cycle optimisation and rational expectations, changes in consumption follow a random walk, with future consumption predicted only by current consumption, not by current income alone. |
| Robert E. Hall: Labor-market frictions | Hall’s work comprises analysis of search frictions, sticky wages, and unemployment fluctuations, and their impact on real economic cycles and policy effectiveness. |
| Michael Woodford: Monetary policy channel | Woodford’s New Keynesian framework (Interest and Prices) provides for the statement that monetary policy operates primarily by steering market expectations of future interest rates rather than merely adjusting the money supply. |
| Michael Woodford: Forward guidance and zero lower bound | Woodford’s work provides for the theoretical foundation for modern central bank communication strategies, including forward guidance, and explains how policy traction is maintained even when short-term interest rates hit zero. |
| Traditional macro-models vs reconstructed framework | The comparison comprises: traditional macro-models (pre-1970s) are based on purely aggregate statistical correlations and use backward-looking or adaptive expectations, with transmission via direct control over monetary aggregates (M1, M2), and are vulnerable to structural policy regime changes (Lucas Critique); the Hall-Woodford reconstructed framework uses microfoundations based on individual utility and profit maximization with forward-looking rational expectations, with transmission via managing interest-rate paths, forward guidance, and inflation targets, and is robust to policy shifts because parameters reflect deep economic preferences. |